

"Mrs. Mercier at Soho Realty made our experience exceptional! She genuinely cares about her clients, communicates every step of the way, and is a pleasure to work with. Highly recommend!"


Get the loan right — and everything that follows gets easier.
— Sharlene Mercier
Real Estate and Mortgage. One professional from application to closing.

Loan officer and real estate agent under one roof. One plan from pre-approval to keys.

I explain every option until you're confident.

Credit challenges. Low down payment. I've got a lender for that.
This is what happens when your lender actually cares whether you keep the house.
2 minutes · No credit pull to check your readiness.
For your unique situation — credit challenges, low down payment, self-employed, starting over. We meet you where you are and guide you to keys in your hand.
JUST STARTING OUT
SELLING TO UPGRADE
RUNNING YOUR OWN BUSINESS
HIGHER PRICE POINTS
BUILDING WEALTH
ALREADY OWN A HOME
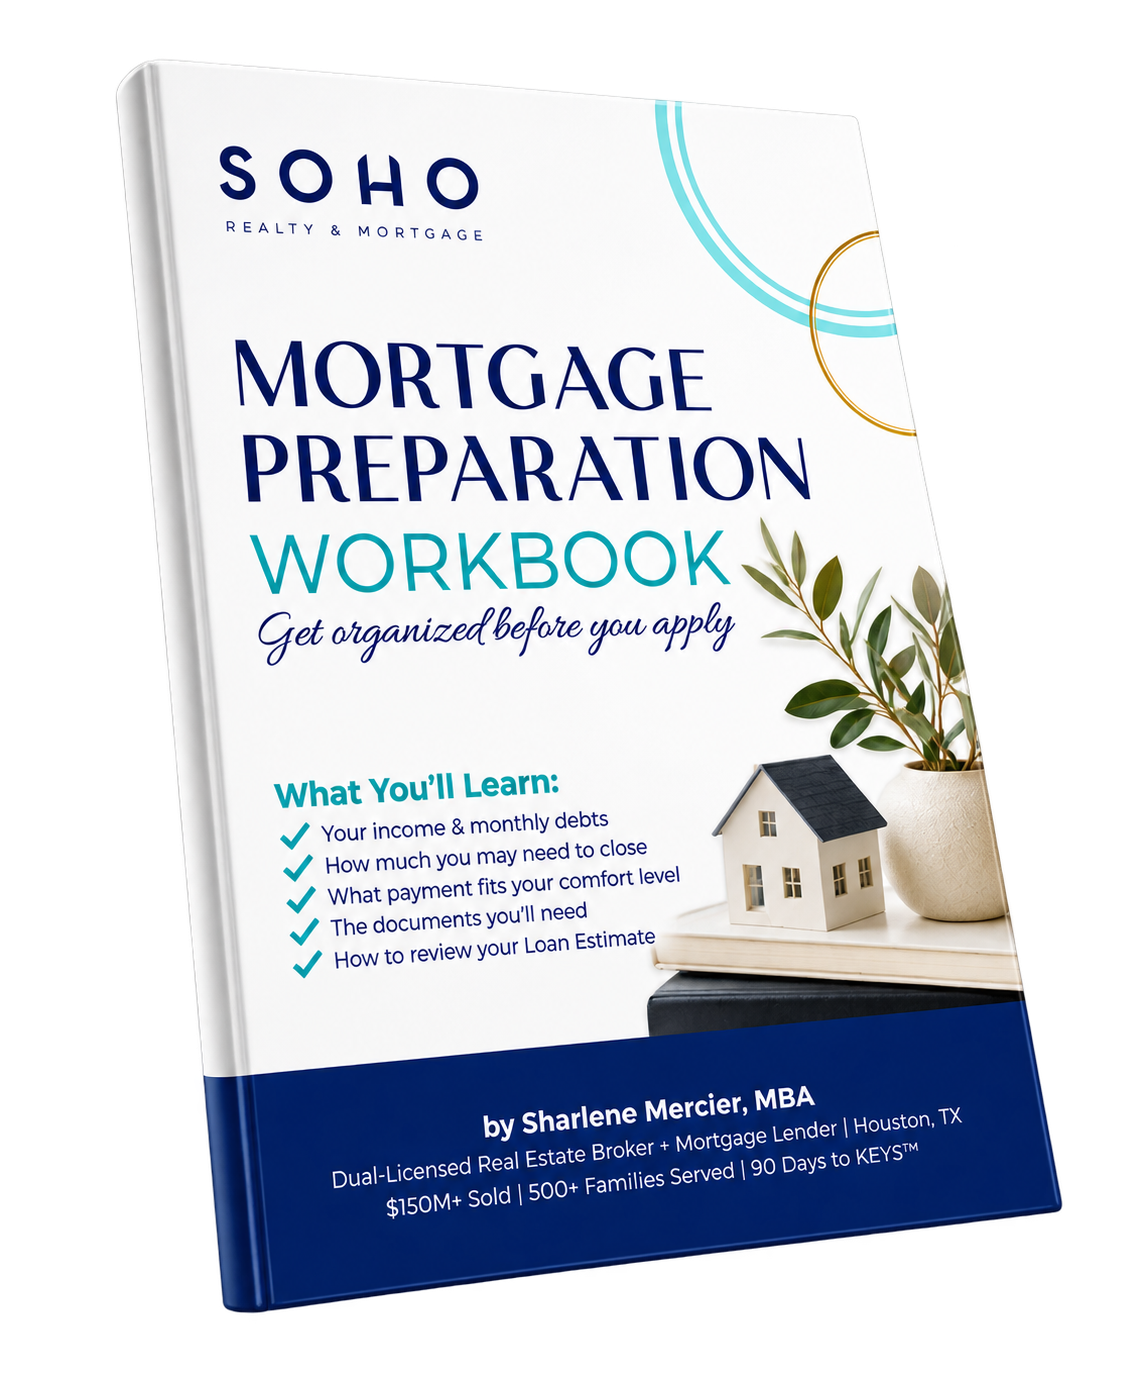
Before you apply for a mortgage, you need to understand more than just your credit score.
This workbook helps you organize the numbers, documents, and financial details a lender will need so you can enter the pre-approval process prepared and confident.
Instant download. Yours to keep. No commitment.
Six things big banks don't do — and we always do.
2 minutes · No credit pull to check your readiness.
When the traditional path doesn’t work, we look at the whole picture and find a smarter path forward.
FIRST-GENERATION HOMEBUYER • SOFTWARE ENGINEER
THE SITUATION
Seven years ago, Katrina experienced unemployment and housing instability. Since then, she built a six-figure career as a software engineer, improved her credit, and grew her savings — making her financially ready to buy a home. As a first-generation homebuyer, she wants to purchase a home not just for herself, but eventually to house her parents and grandmother.
THE OUTCOME
After attending Sharlene's webinar, Katrina followed her personalized action plan and became a homeowner in 45 days. She purchased a two-story, four-bedroom home in a quiet Cypress-area community — complete with a game room, open kitchen, spacious backyard, and trails.
She became the first homeowner in her family, proof that a difficult chapter doesn't have to determine the ending.
“I was like, ‘Wow, this is possible.’ I just did everything on that plan. And now I’m a homeowner.”
FROM A BUILDER’S DENIAL TO HOMEOWNERSHIP—TOGETHER
THE SITUATION
Trichonne had owned a home before, but setbacks and a lender denial made buying again feel uncertain — could her credit, income, and down payment work with today's prices? Her daughter Nia had never owned a home, turning Trichonne's question into a bigger one: could they become homeowners together?
After discovering Sharlene on social media, Trichonne attended SOHO's workshop to find out.
THE OUTCOME
A strategy call reviewed Trichonne's numbers and mapped a clear path. Within 3 days, she had verified approval and learned she could use her 401(k) toward the down payment. She and Nia chose new construction and closed within 30 days.
For Trichonne, it was a comeback. For Nia, it was her first home. For both, it was the start of building equity and a stronger financial foundation.
“The most surprising thing was that I could actually afford to purchase a home. Realizing that I could actually get a home was the most impactful thing for me.”
FROM WATCHING ON LINKEDIN TO BUYING ON HER OWN
THE SITUATION
For years, Althea rented while rebuilding her life after divorce and raising her daughter. She had a good income and a 401(k), but fear and uncertainty kept her waiting. Buying a home felt like something for later.
Then a SOHO video appeared in her LinkedIn feed and changed how she saw rent, investing, and what was possible for her family.
THE OUTCOME
Althea reached out simply to thank Sharlene for the information. That message became the start of her homebuying journey.
With coordinated real estate and mortgage guidance, she felt informed and supported from start to finish. Today, she owns her home and sees wealth building differently: she can do more—and go bigger.
"The experience was seamless. Everything moved a lot faster than I expected, and they were there every step of the way.”
Every woman above started exactly where you are. They weren't alone. Neither are you.
2 minutes · No credit pull to check your readiness.
Honest answers. No mortgage-broker speak.
Lower than you think. FHA loans can go down to 580, sometimes 500 with the right lender. The score is one factor — not the whole picture. Income, debt-to-income, savings, and timing all matter too.
The amount you need for a down payment depends on the loan program and your financial situation. Some buyers may qualify with as little as 3% down, while others may choose to put more down to lower their monthly payment or avoid certain costs. The goal isn’t to put down the most money possible, but to choose a down payment that keeps you financially comfortable after you close.
If you’re self-employed or have non-traditional income, you can still qualify for a mortgage. The key is showing consistent, documentable income, and the lender may look at your tax returns, business records, bank statements, or other income documentation depending on the loan program. Being self-employed doesn’t disqualify you, but it can require a little more planning to make sure your income is presented correctly.
A pre-approval is when a lender reviews your income, credit, debts, and finances to determine how much you may qualify to borrow. You need one because it helps you understand your real buying range, shows sellers you’re a serious buyer, and helps you shop with confidence instead of guessing what you can afford.
A pre-approval can often be completed within 24 to 48 hours once you provide the necessary documents. The timeline depends on how quickly we receive and verify your income, assets, credit, and other financial information.
A mortgage pre-approval uses a hard credit inquiry. We run it only after your complete application and all intake documents are submitted and approved.
2 minutes. 8 questions. A clear path forward.
Share My QR |
|
